Fusion – the Swiss FinTech business accelerator – exists to shape innovation in financial services by combining up-and-coming tech talent with Swiss state-of-the-art financial know-how. As a Fusion member, Notz Stucki is actively involved in the process.(more…)
7 questions to a start-up: Delio
Fusion – the Swiss FinTech business accelerator – exists to shape innovation in financial services by combining up-and-coming tech talent with Swiss state-of-the-art financial know-how. As a Fusion member, Notz Stucki is actively involved in the process.(more…)
Chart of the Month – CAPE–ability in question
CAPE–ability in question
« In theory there’s not much difference between practice and theory – but in practice, there is. » Yogi Berra.
Source: Bloomberg, Notz Stucki
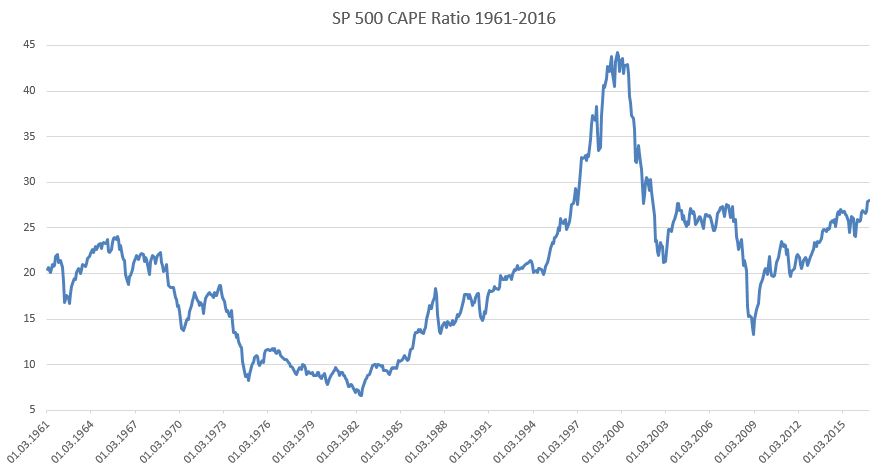
More and more warnings are being sent about the unsustainability of the current CAPE ratio for the SP500 and that a correction should occur, based on the very high level of the famous CAPE – the Cyclically Adjusted Price Earnings ratio.
This valuation measure of the equity market, brought by John Campbell and Robert Shiller in 1988, consists in taking a long term (typically 10 years) average of real earnings to calculate the Price Earnings ratio of a given equity index in order to smooth out short term profits’ volatility.
The economists did not set an absolute level of cheapness or expensiveness for their ratio, but the frequently mentioned levels are 20 (expensive) and 12 (cheap). Based on these numbers, investors should be wary of buying stocks when the CAPE stands above 20 (currently it is close to 28), and should on the contrary increase their exposure when the CAPE hovers below 12.
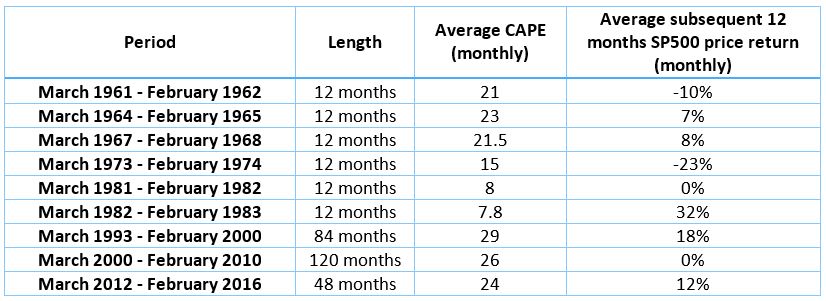
Our friend Jeffrey Saut, chief strategist at Raymond James Associates, has repeatedly questioned the accuracy of this measure during the last few years, so we’ve decided to crunch the numbers and simply look at some historical data to assess the relevance of the current warnings about the CAPE. The table here below recapitulates some periods with their associated CAPE and the monthly average of the subsequent 12 month price return on the SP500.
Based on these numbers, the conclusion is pretty straightforward: the predicting power of the CAPE for future returns is extremely poor if you set the 20 and 12 levels for dearness or attractiveness. Maybe the most striking example is between 1993-2000 when the average CAPE was 29, a record, but the average SP500 return of any given 12 month period during this time frame was a whopping 18%!
Even though CAPE is high today we think it has to be mitigated by a few factors:
Interest rates ar still at historical lows, propping up valuations.
Today’s CAPE includes the terrible 2008-2009 period when earnings were decimated, which should correct after 2019 CAPE calculations.
The SP500 today is less cyclical than it used to be. There’s dominant group of sector like non -cyclical Information Technology, Healthcare, Consumer Staples which were not so highly represented in the past, when Industrials, Energy and Consumer Discretionary had much higher weightings.
History seems to tell us that, as shown in the table, there’s no golden rule for assessing an alarming level for the CAPE.
The well-known CAPE theory would incite us to step away from US equities today, but we beg to differ.
Practice, as Yogi Berra said, does not necessarily go in sync with theory!
Chart of the month: March Edition
What is cheap? what is expensive? Choose your camp!
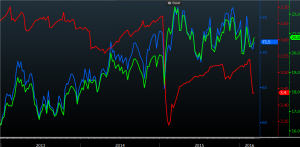
Company 1. Red line: trailing 12 month Earnings per Share, Green line: Price Earnings Ratio, Blue line: share price
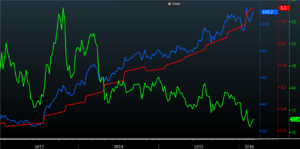
Company 2. Red line: trailing 12 month Earnings per Share, Green line: Price Earnings Ratio, Blue line: share price
So you have here two charts showing the evolution over more than 3 years of earnings, PE multiple and price for two distinct companies. One is supposedly a safe haven stock (company 1), paying a good dividend, on which losing money seems almost impossible whereas the other one (company 2) is that kind of “hype” stocks which, at some point should fall off a cliff because of overvaluation.
An equity investor must first and foremost look at the stream of earnings a company can generate in order to decide whether to buy this or that stock. Dividends are important, but come after earnings because when a corporation generates profit and does not pay a dividend, this profit goes straight up into shareholder equity, which means that in theory profits paid in dividends or retained into the company’s balance sheet should not impact the attractiveness of a listed stock.
We have seen an incredible and almost unprecedented appetite during the last 3 to 5 years for quality stocks, with predictable earnings and reasonable dividends. This seems quite logical in an unstable environment. Investors are skeptical about the economic cycle, about the financial system, about capital expenditure, and so on, therefore buying into blue chips, generally in the consumer staples sector, tends to be the only acceptable investment. And in most cases, they were right! Those large caps (Nestlé, P&G, Colgate, Unilever, Coca-Cola and others) have performed honorably, paid dividends, and were quite resilient when markets were nervous.
In the first chart, you can see a company which has seen its share price go from 60 to 71, its PE multiple climb from 16.5x to 20.8x, and its EPS slip from 3.65 to 3.4.
In the second chart, share price soars from 40 to 109, but EPS explodes from 0.75 to 3.3…. so mechanically the PE multiple falls from 48 to 33.
In our view, the first company does not deserve such a valuation and favorable performance if one takes out the extraordinary fall in interest rates which has magnified the stable nature of its business. There should be no other explanation because in a “normal” environment, a corporation which sees its earnings headed down should not see its share price and PE climb.
What about the second company? It was expensive when it traded at 48 times earnings, but over the considered period earnings have been multiplied by 4.4 while share price “only” rose 2.7 times. It still trades at 33 times earnings but will soon get cheaper than company 1 thanks to EPS growth.
Which one would you buy today? Indeed interest rates could still fall further and help company 1’s valuation remain at current levels (or higher), but it seems difficult to imagine that the stock can trade at a substantially higher PE as long as earnings don’t grow. We largely prefer company 2 because, as said before, the stream of earnings plays in favor of the investor. At the end of the day, the winners in equity markets are those who increase earnings, not those who benefit from external forces to drive their multiple on the upside.