Quarterly Investment Review

‘It’s ludicrous that a government can borrow at a negative interest rate and doesn’t take advantage of that.’ Sajid Javid, UK Chancellor, 7.12.19

At the peak in 2019 $17 trillion of global bonds carried a negative yield. One shouldn’t lose sight of the fact of how odd it is to pay for owning bonds. When the German 10-year Bund yield fell to -0.7% it meant an investor would receive €93 in 10 years’ time for the €100 invested today. By comparison in previous periods of financial stress bund yields had fallen to -0.1% in 2016, 1.2% in 2012 and 3% in 2008. It is confounding that these negative yields occurred during a period of economic expansion and employment growth, plus now the promise of coordinated fiscal expansion globally, all of which could see the competition for funding drive up the cost of money. Even Greek debt carries a negative yield. In 2012 the markets were closed to lending to Greece at any price, but now lenders pay for the privilege to lend their money for maturities under six months. Elsewhere in November Angola issued $3 billion of debt for 10 and 30 year maturities that was three times oversubscribed, despite a four year recession which has led to its debt to GDP jumping to 100%, a tumbling currency and the largest credit facility that the IMF has extended to an African country.

These historically low yields derive from Central Banks attempts to revive growth through reducing the cost of debt. However there is increasing evidence that rather than persuading people to spend, negative interest rates are persuading them to do the opposite, to save. Likewise the effectiveness of this debt is diminishing, generating about half as much GDP growth per unit of debt in the last decade as it did in the one before that. Instead the liquidity has flowed into financial assets. For example in the first quarter of 2019 the Eurozone’s 3 largest economies of Germany, France and Italy added just €6 billion of growth, compared to their stock market capitalisations increasing by €516 billion. We seem to have reached the point of policy impotence with the monetary policies of the last decade. Hence governments are looking increasingly to fiscal stimulus measures, which are not bond friendly. As the quote at the top of the page shows populist politicians have spotted the opportunity to gorge on these historically low borrowing costs in order to finance the promises that helped get them elected. Austerity has failed in political terms, for example, in the US the deficit for 2020 is estimated at $1.2 trillion, which is less than the $1.4 trillion in 2009, but that was a year of crisis. Such a deficit extending into prosperous times suggests that it is structural, and will be very hard to reduce. Entering 2020 the US will have significant monetary and fiscal stimulus at a time of full employment as President Trump seeks to turbo charge the economy for his re-election campaign. This twin stimulus is occurring at a time when both core and median consumer prices are at decade highs. Elsewhere the Japanese government announced a $120 billion spending package, and across Europe governments are starting to accept the need for similar efforts. As debt issuance soars and growth slows common sense suggests that inflation will pay this money back eventually. The internet and globalisation have led to a long period of disinflation, but tight employment and populist support for increasing the minimum wage puts pressure on wages, and prices are starting to creep up in some areas. For example the prices of the fifty most sold items by Wal Mart rose 5.2%. Migration controls and trade conflicts are also potentially inflationary. A change in sentiment would affect all markets. At the end of 2018 when interest rates started to rise and liquidity tightened it created an extremely challenging environment for investors. The ingredients for a repeat of this situation remain.

Sentiment over the trade war between the US and China has fluctuated over the year. The final outcome of the negotiations were not clear at year end but even if a settlement is reached concerns will linger. When it started in early 2018 there were hopes that the issues would be settled quickly, but what first appeared to be a spat over the trade deficit has now revealed itself to be a confrontation across many issues including military influence, technological capacity, financial access as well as trade imbalances. Short term the uncertainty is likely to be compounded by the upcoming Presidential election in the US, but longer term it is shaping up to be a multi-year problem. To underlie the seriousness of this situation one has to consider that in passing the Hong Kong Act Republicans and Democrats, who can hardly bear to be in the same building together, came together in near total unanimity and speed, to pass the Act which is a direct insult to China. Trade disputes inject deep uncertainty into the business outlook. To the extent that this one threatens globalisation it is stagflationary because it lowers long term global growth potential, and introduces inefficiencies and costs as decisions are taken more from political than economic motives. On China’s side they will accept slower growth in so far as it is consistent with social stability, but that growth will be focused more on their domestic economy, and therefore less of a boost to global activity.

Click here to download the full document.
Quarterly Investment Outlook

The dominant feature of financial markets remains the low yields offered by bond markets, and in particular the increase in the quantity of bonds which carry negative yields.

In the third quarter world markets as measured by the MSCI World were flat. Year to date the S&P is up 18.7% and the MSCI World is up 15.7%, though much of this performance is recovering the steep losses of the fourth quarter of last year. Over the past twelve months the S&P is 2.1% and the MSCI World is down slightly.

The dominant feature of financial markets remains the low yields offered by bond markets, and in particular the increase in the quantity of bonds which carry negative yields. Approximately $15 trillion of debt is trading in the market with a negative yield, representing about a third of all Sovereign debt, which is the liquid part of the market. Perhaps more importantly about two thirds of all Sovereign bonds now offer a negative real yield (i.e. after taking inflation into account). This is historically unique, and truly bizarre in which one of the best investments this year would have been to buy assets that were already negative yielding at the start of the year, and therefore had a 100% guarantee to produce a loss if held to maturity. In such an environment investors have been desperate to find quality bonds with a positive yield.

Getty Image

The US bond market has been one of the few that still does, partly explaining the strength of the dollar. The plunge in yields has led to some prices which would have been thought impossible a few years ago. For example at the end of 2017 Austria issued a 100 year bond with a coupon of 2.1%. This year it has risen 64%, in the third quarter alone rising by 23%. It now yields 0.8% for the remaining 98 years. Can a yield of 0.8% in a fiat currency that was only launched twenty years ago be deemed truly safe? A lot can happen in 100 years, and in the last 100 years a lot did happen in Austria. If interest rates were to rise by 1% it would take 26 years to break even on the current coupon. Equally bizarre is the performance of gilts which have soared despite the Brexit chaos, as the UK still offers a positive yield which is relatively attractive against other European countries where one pays for the privilege of lending to their governments. Such countries now include Latvia, Ireland and Slovenia, while Bulgaria, Lithuania and Spain are a hair’s breadth from joining them in the negative yield club. The implications of these yields are wide ranging. Vast amounts of money is sacrificing purchasing power for the next decade, for example, at minus 1% a Swiss pension that buys the ten year bond guarantees a capital loss of 10%. Worse with the Swiss interest rates negative out to 50 years there are no Swiss government bonds available with a positive nominal yield, meaning that investors will lose money in any Swiss government bond held to maturity. How do such countries provide for the social claims of a rapidly ageing world? Even stranger is that this is taking place at a time of growth not recession. For comparison in the depths of the 1930’s US depression when industrial production declined 25% the 10-year yield fell only to 2.31%. Today world growth is slowing but it is still positive. Moreover monetary policy is loose, fiscal stimulus is being advocated by most governments and wages are rising. Many of the conditions necessary for inflation are present at a time when the fixed income investor has no yield to cushion them. The last time fiscal policy was expanded at a time of full employment was in the early 1970’s, an equally febrile political period, and inflation became a problem for the next decade. The integration of the labour force of the Emerging Markets mean that labour has less bargaining power than that period, but bond prices do not provide protection against a rise in inflation or the cost of living.

Click here to download the full document.
Quarterly Investment Outlook

The performance and current level of the world bond markets are extraordinary.
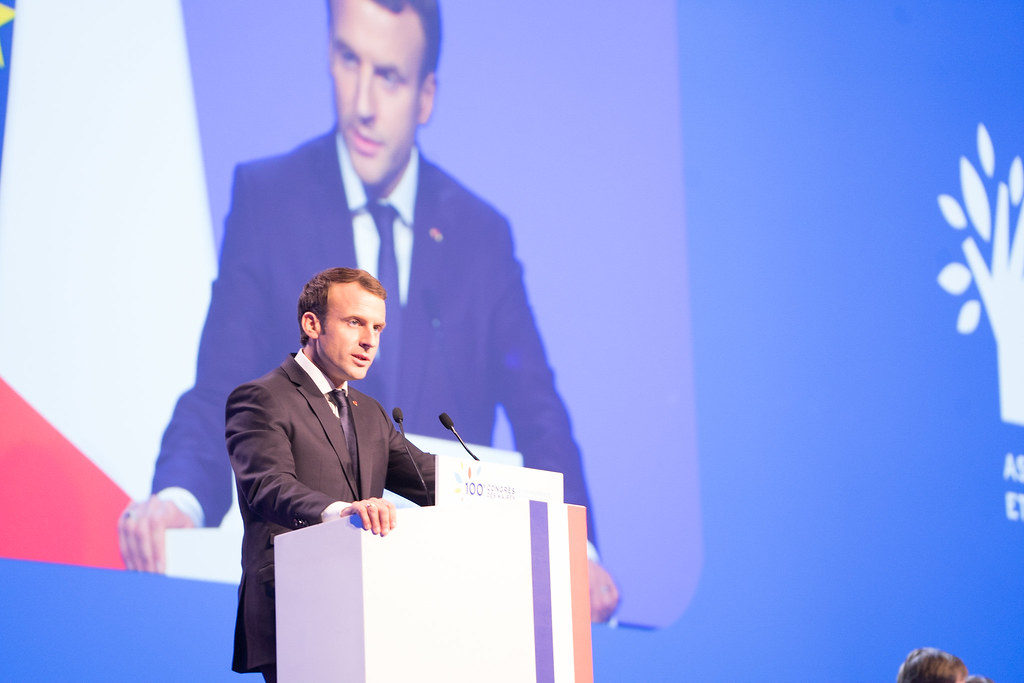
President Emmanuel Macron

The French example illustrates the bizarreness of this situation. French government debt reached €2.3 trillion at the end of 2018 and is estimated to expand by a further €80 billion this year, largely as a result of President Macron’s concessions to the gilet jaunes protestors. This puts its debt to GDP ratio at close to 100%, not as large as Italy’s but France’s debt is growing more quickly. France has not run a budget surplus since 1974 (before the current President was born), state spending is the highest of any country in the developed world at 56% of GDP, and it will be hard to raise taxes further as they are already the highest in the developed world at 46% of GDP having just overtaken Denmark, and the gilet jaunes movement indicates that the limits have been reached. It will also be challenging to grow out of this problem as economic growth has been lacklustre for several years. Most concerning of all is that France owes its debt in a currency that it does not control and cannot print, and most of it is borrowed from outside France (unlike say Italy where most of the debt is held internally). France has an outstanding credit record, not having defaulted since 1812, but it stands out among the negative yielding sovereign issuers for the combination of the poor profile of its finances and its inability to print money independently. It is irrational that such an issuer is paid for the debt it issues. For context, in the depths of the Great Depression of the early 1930’s when industrial production fell by a quarter the US ten year bond bottomed at a yield of 2.31%. Japan and a number of European countries’ debt markets are suggesting depression conditions, even though their economies are still growing.

Click here to download the full document.
Investment Outlook Q1 2019

Where are the gilets jaunes of the bond market?

As the various Central Banks peddle back on their quantitative tightening program the financing needs correspondingly grow.  Buyers will need to be found at a point when competition for debt is rising. Global debt has climbed by $100 trillion since the financial crisis and sits around $240 trillion. China has been a big buyer of US Treasury bonds in the last two decades but as its economy slows and reorients from an export model towards one more focused on domestic consumption it will want to keep its savings at home and will have less surplus funds to invest abroad. Likewise the energy-producing Middle East has a demographic boom, and with oil prices lower and an expanding social welfare budget it is having to come to the capital markets for financing, becoming a competitor for funds rather than provider of them.  Perhaps the greatest risk in debt markets lies in the corporate sector. US companies have been prolific issuers of new debt, much of it poor quality. The ‘investment grade’ market is far larger today than it was heading into the 2008 crisis. When a recession eventually arrives a lot of this debt will turn sour.

Investors face a problematic environment. Bonds are unattractive, and in some cases unsafe. This leaves equities as the best option, but the emphasis on careful stock picking has increased. Markets have had a strong quarter so a consolidation period should be expected.  There is attractive value in a number of areas but this will require patience to unlock. With the US market richly priced the longer term opportunity should be in Emerging Markets, but this is unlikely to be realised until the US China trade dispute has a resolution.

Click here to download the full document.
Investment Review Q3 2018

“I think Trump may be one of those figures who appear in history from time to time to mark the end of an era and to force it to give up the old pretences.”

Henry Kissinger. 21.7.18

The third quarter was difficult in financial markets. Tightening liquidity as a result of the Federal Reserve’s increase in interest rates, escalating trade tensions, a rising oil price, and heightened worries on European stability with Brexit talks in a quagmire and a threat of Italy exiting the EU, all combined to undermine sentiment. However once again markets outside the US suffered most and by the end of the quarter the US equity market was at/near its highs. The US stock market is benefiting from a strong economy and the tax cuts that the Trump Administration achieved at the end of 2017. Goldman’s have estimated that share buybacks could reach almost one trillion dollars this year. This performance has been despite the rise in interest rates and bond yields as the ten-year rate rose to 3.05%. Outside the US surplus liquidity has been drained from the system exposing the weakest links, Argentina and Turkey’s currencies crashed and other Emerging Market assets suffered. This sharp divergence has been a feature of the last ten years. On the tenth anniversary of Lehman’s collapse and the ensuing financial crisis the surprise has been that while the US has had a weak economic recovery it was accompanied by a soaring stock market. The comparison to the Japanese experience following their collapse in 1990 could not be starker. Ten years after the Japanese bubble burst the Japanese Topix index was half its pre-crash level, while the S&P is up more than twice, and more than four times off its lows. Their bubbles were different, but a significant driver of the S&P’s recovery was the enormous share buybacks American companies have undertaken which Goldman Sachs estimates at $4.5 trillion over the last decade. This buyback program has been turbo charged by the Trump tax cuts with estimates that they will approach $1.5 trillion in 2018 alone.

Please click here to download the entire document.


Investment Outlook Q3 2018

At 10 times revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard for a company with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes that you pay no taxes on your dividends, which is kind of illegal. And that assumes with zero R&D for the next 10 years I can maintain my current revenue rate….what were you thinking.

Scott McNealy, CEO of Sun Microsystems at the time of the dotcom crash when the shares were selling at 10 times sales.

Scott McNealy

At mid-year world bond and equity markets have struggled, with bonds delivering a slightly negative return and equities fell 1.3% as measured by the MSCI World Index, a poor return given that S&P earnings are estimated to increase by 25% this year (largely thanks to the tax cut at the end of 2017). Emerging Markets have been particularly poor performers. The reason is that liquidity has been tightening. In the US, quantitative easing is being steadily drained from the system at a rate of $30 billion a month, which rises to $40 billion from July 1st, and then $50 billion on October 1st. The oil price has risen about 30% over the past year, which results in a severe drain of liquidity. Labour markets have also been tightening creating some wage pressure and with inflation measures trending higher, bond yields have risen. On top of all this investors have been unnerved by a number of political developments, most obviously the trade disputes as the Trump Administration has now specified particular areas against China and Europe, and in Europe an Italian political crisis has threatened the stability of the Eurozone. The US tax cuts achieved at the end of last year, are a clear positive for the stock market, representing a substantial infusion of cash to shareholders. However tightening liquidity, the threat of protectionism and inflation are unfriendly for markets, and constitute significant headwinds. Together they have made the outlook for financial assets much more murky than was the case a few months ago. All markets have been buoyed on an ocean of liquidity for the past few years, so as that is removed a major support to asset prices disappears.

It is unusual to have trade wars when activity is expanding; generally they are a reaction to weak economic activity.

Please click here to download the entire document.

Investment Outlook Q2 2018

After the strong performance in almost every equity market in 2017, characterised by a remarkable lack of volatility, the financial weather changed abruptly in the middle of the last quarter. The trigger was a stronger than expected jump in US hourly wages in January. This inflationary fright rattled markets and led to a steep sell off in bonds and equities. As the quarter progressed a less alarming picture of inflation emerged. However markets had become extended and they have not settled down, while further anxiety was caused by President Trump threatening trade tariffs which could upset the global trade system that has been in place for the last thirty years, and a scandal involving Facebook, one of the market leaders.

President Trump, Mark Zuckerberg

Markets took Trump’s election victory calmly with the S&P 500 recording gains in every month of 2017. One of the positive features of his Administration has been the reduction of regulations. For example the number of pages of the Federal Register has risen steadily since World War II. In the past year they have dropped from almost 100,000 pages to 54,153, partly due to the Trump program requiring two regulations to be cut for every one added. They cut more on top of that. This is a dramatic change that gives American business considerably more operating flexibility. The tax cut he pushed through in December led to a spike in the stock market in December and January, but the inflation number and some geopolitical rumbles caused the market to be more sceptical of Trump. On the economic side the concern for the bond market is the substantial supply of bonds that will be needed to finance the recent tax cuts. The US budget deficit is forecast to expand from 3.5% to 6%, at a time when the Federal Reserve is withdrawing its policy of QE by reducing their purchases of bonds at a rate that will reach $50bn a month by October, so the bond market faces significant negative changes to both supply and demand. The tax stimulus is coming at a time of nearly full employment so the market is particularly sensitive to wage increases. On top of this the market must contend with the capricious nature of the President, whose policies frequently appear to be unanchored. It is never quite clear what his strategy is, and he has shown a far greater tendency to shift position on a policy than previous incumbents. One example of this is there has been an uncomfortably high turnover of White House staff during his tenure. This is unsettling for markets which prefer clear signals from global leaders on which they can base their decisions. President Trump also seems uninterested in the global bodies that have dominated the world over the past half century such as WTO, NATO and the UN. Whatever the merits of his view that these organisations constitute a bad deal for the US, the danger arises that if the US show less commitment to them then the world is left without a night watchman at a time when security fears are growing, creating further uncertainty. Another concern is the proposal of tariffs being imposed by the US. Anything that inhibits free trade is a negative, so the threat of protectionism weighed on the market at the end of the quarter. However the greatest threat may come from the changes that President Trump made to his senior team in March, which points to a far more hawkish approach on foreign policy, particularly towards countries that the US perceive as rogue states like North Korea and Iran. As a consequence geopolitical tensions have risen considerably this year. While any serious international rift effects markets, an action against Iran would directly affect the oil price and is therefore of more concern.

Please click here to download the entire document.