Investment Review Q3 2018

“I think Trump may be one of those figures who appear in history from time to time to mark the end of an era and to force it to give up the old pretences.”

Henry Kissinger. 21.7.18

The third quarter was difficult in financial markets. Tightening liquidity as a result of the Federal Reserve’s increase in interest rates, escalating trade tensions, a rising oil price, and heightened worries on European stability with Brexit talks in a quagmire and a threat of Italy exiting the EU, all combined to undermine sentiment. However once again markets outside the US suffered most and by the end of the quarter the US equity market was at/near its highs. The US stock market is benefiting from a strong economy and the tax cuts that the Trump Administration achieved at the end of 2017. Goldman’s have estimated that share buybacks could reach almost one trillion dollars this year. This performance has been despite the rise in interest rates and bond yields as the ten-year rate rose to 3.05%. Outside the US surplus liquidity has been drained from the system exposing the weakest links, Argentina and Turkey’s currencies crashed and other Emerging Market assets suffered. This sharp divergence has been a feature of the last ten years. On the tenth anniversary of Lehman’s collapse and the ensuing financial crisis the surprise has been that while the US has had a weak economic recovery it was accompanied by a soaring stock market. The comparison to the Japanese experience following their collapse in 1990 could not be starker. Ten years after the Japanese bubble burst the Japanese Topix index was half its pre-crash level, while the S&P is up more than twice, and more than four times off its lows. Their bubbles were different, but a significant driver of the S&P’s recovery was the enormous share buybacks American companies have undertaken which Goldman Sachs estimates at $4.5 trillion over the last decade. This buyback program has been turbo charged by the Trump tax cuts with estimates that they will approach $1.5 trillion in 2018 alone.
Please click here to download the entire document.
 

Investment Outlook Q3 2018

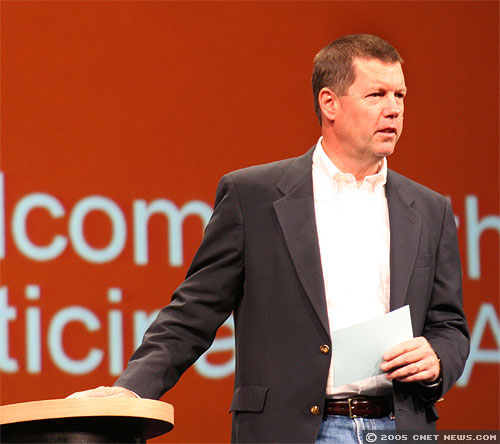
At 10 times revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard for a company with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes that you pay no taxes on your dividends, which is kind of illegal. And that assumes with zero R&D for the next 10 years I can maintain my current revenue rate….what were you thinking.

Scott McNealy, CEO of Sun Microsystems at the time of the dotcom crash when the shares were selling at 10 times sales.

Scott McNealy

At mid-year world bond and equity markets have struggled, with bonds delivering a slightly negative return and equities fell 1.3% as measured by the MSCI World Index, a poor return given that S&P earnings are estimated to increase by 25% this year (largely thanks to the tax cut at the end of 2017). Emerging Markets have been particularly poor performers. The reason is that liquidity has been tightening. In the US, quantitative easing is being steadily drained from the system at a rate of $30 billion a month, which rises to $40 billion from July 1st, and then $50 billion on October 1st. The oil price has risen about 30% over the past year, which results in a severe drain of liquidity. Labour markets have also been tightening creating some wage pressure and with inflation measures trending higher, bond yields have risen. On top of all this investors have been unnerved by a number of political developments, most obviously the trade disputes as the Trump Administration has now specified particular areas against China and Europe, and in Europe an Italian political crisis has threatened the stability of the Eurozone. The US tax cuts achieved at the end of last year, are a clear positive for the stock market, representing a substantial infusion of cash to shareholders. However tightening liquidity, the threat of protectionism and inflation are unfriendly for markets, and constitute significant headwinds. Together they have made the outlook for financial assets much more murky than was the case a few months ago. All markets have been buoyed on an ocean of liquidity for the past few years, so as that is removed a major support to asset prices disappears.

It is unusual to have trade wars when activity is expanding; generally they are a reaction to weak economic activity.

Please click here to download the entire document.